


The Strategic Outlook for Central Bank Digital Currencies CBDCs in Latin America and the Caribbean
Financial institutions across the Americas are navigating a pivotal shift as they weigh the integration of sovereign digital assets against the rapid expansion of private-sector payment rails. While central bank digital currencies cbdcs in latin america and the caribbean represent a formal move toward state-backed monetary innovation, the decision to adopt these tools involves complex trade-offs between regulatory control and operational speed.
Core trade-offs in regional payment modernization
The primary tension for regional stakeholders lies in the balance between regulatory oversight and technical agility. Central banks prioritize monetary sovereignty, anti-money laundering (AML) compliance, and financial stability. These requirements often lead to deliberate, slower development cycles compared to private fintech solutions. Private networks frequently leverage existing high-speed infrastructure to solve liquidity issues in real-time, effectively bypassing the bureaucratic hurdles often associated with government-led projects.
Key considerations for financial institutions
- Regulatory Compliance: CBDCs provide built-in AML and KYC frameworks directly mandated by state authorities, reducing the compliance burden for some institutions.
- Operational Speed: Private networks currently lead in transaction throughput and offer API-ready integration that aligns with modern developer workflows.
- Interoperability: Private stablecoins often bridge legacy banking systems and decentralized finance (DeFi) more effectively than early-stage CBDC pilots.
- Counterparty Risk: CBDCs eliminate settlement risk by utilizing the central bank's balance sheet, providing a level of security that private assets cannot match.
Evaluating Regional Digital Asset Adoption
The implementation of central bank digital currencies cbdcs in latin america and the caribbean provides a distinct value proposition in areas where legacy banking systems struggle, particularly in offering a stable, low-cost medium of exchange for underbanked populations. By digitizing national currency on a central bank-controlled ledger, these initiatives aim to reduce cash reliance and mitigate the volatility risks inherent in private stablecoins. The success of the Sand Dollar in the Bahamas serves as a primary case study for how CBDC architecture can lower barriers to entry for digital wallets in island economies.
Financial inclusion and infrastructure challenges
In larger economies, such as Brazil with the DREX project, the focus has shifted toward tokenizing assets to improve the efficiency of complex financial contracts. However, a significant hurdle remains: ensuring that the infrastructure is accessible to populations without reliable high-speed internet or modern smartphone hardware. While the potential for inclusion is high, the physical reality of regional connectivity gaps remains a primary constraint for mass adoption.
Cross-border settlement efficiency gains
Regional trade in Latin America is frequently hampered by high costs and slow settlement times due to reliance on traditional correspondent banking. A regional framework could theoretically reduce these frictions by enabling direct, atomic settlement between central banks. This approach would bypass the fragmented network of commercial banks that currently adds days to transaction times, potentially lowering the cost of intra-regional trade significantly.
Private stablecoin and real-time payment alternatives
Private-sector rails often outperform government projects in terms of user adoption and technical flexibility. Systems like Pix have already established the necessary trust and network effects that any new digital currency would need to build from scratch. These private networks utilize modular API architectures, allowing for rapid integration with existing merchant software and point-of-sale systems. Firms looking to scale these solutions often require digital marketing cryptocurrencies expertise to build user trust.
Latency and interoperability advantages
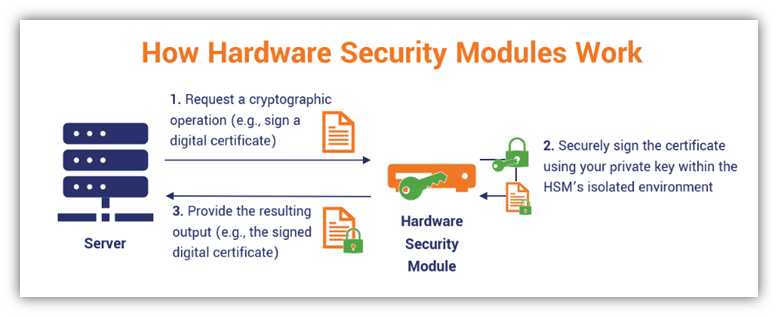
Government frameworks often require custom-built, proprietary hardware security modules (HSMs) and strict adherence to central bank protocols. This can introduce latency and limit interoperability with broader global DeFi ecosystems. In contrast, private networks are built for modularity, allowing institutions to switch providers or protocols if one becomes inefficient, thereby offering a degree of operational flexibility that sovereign systems currently lack.
Decision matrix for regional financial institutions
Institutions must weigh the long-term stability of government-backed infrastructure against the immediate utility of private networks. For cross-border trade, sovereign digital assets offer a lower risk of counterparty failure. Conversely, domestic retail payments are currently better served by established real-time payment systems that have already achieved critical mass.
| Feature | CBDC | Private Stablecoin | Real-Time Payments |
|---|---|---|---|
| Settlement Finality | High (Central Bank) | Variable | High (Bank-backed) |
| Regulatory Oversight | Total | Limited | Moderate |
| Implementation Cost | High | Low | Moderate |
Frequently Asked Questions
Distinctions between a CBDC and a cryptocurrency
A CBDC is a centralized digital liability issued and regulated by a nation's central bank, whereas cryptocurrencies are typically decentralized and operate on public, permissionless blockchains without government backing.
Legal tender status of CBDCs
Yes, CBDCs are designed to be legal tender, meaning they are recognized by law as a valid means to settle debts and make payments within the issuing country.
Impact of CBDCs on commercial banking
CBDCs can potentially disintermediate commercial banks by allowing citizens to hold deposits directly with the central bank, which may impact the banks' ability to fund loans through traditional customer deposits.
Offline functionality of digital currencies
Some designs incorporate offline functionality through secure hardware elements, such as smart cards or specialized mobile chips, allowing for transactions without an active internet connection. For those building these fintech products, digital marketing skills are essential for market penetration.
Primary risks associated with implementation
Key risks include cybersecurity vulnerabilities, potential threats to financial privacy, the risk of bank runs during financial crises, and the technical complexity of integrating with legacy systems.
Operational models for implementation
Implementations typically follow one-tier (direct), two-tier (intermediary), or hybrid models, where the two-tier model is most common, involving commercial banks as intermediaries between the central bank and the public.

