


Core architectural frameworks for when a central bank digital currency cbdc is implemented through which of the following models
When a central bank digital currencies cbdcs in latin america and the caribbean is implemented through which of the following models—direct, indirect, or hybrid—the structural choice defines how the central bank interacts with end-users and how the ledger is maintained across the financial ecosystem.
Direct versus indirect issuance models
In a direct model, the central bank manages the entire ledger, including retail accounts and transaction processing. This approach minimizes intermediary risk but places an immense operational burden on the central bank to handle customer service and compliance. Conversely, the indirect model—often called a two-tier system—relies on commercial banks to manage retail accounts. Here, the central bank only tracks wholesale balances, delegating the complexities of retail interaction to private institutions.
Hybrid and two-tier system architectures
Hybrid architectures seek a middle ground by allowing the central bank to maintain a copy of the retail ledger while delegating operational tasks to commercial intermediaries. This ensures that if a commercial bank fails, the central bank retains the data necessary to restore user funds. The two-tier system remains the most common choice for major economies because it preserves the existing commercial banking business model while introducing digital central bank money.
Technical requirements for CBDC infrastructure
Selecting an implementation path requires evaluating the underlying infrastructure, specifically the choice between distributed ledger technology (DLT) and centralized databases. Each choice dictates the speed, security, and scalability of the resulting system.
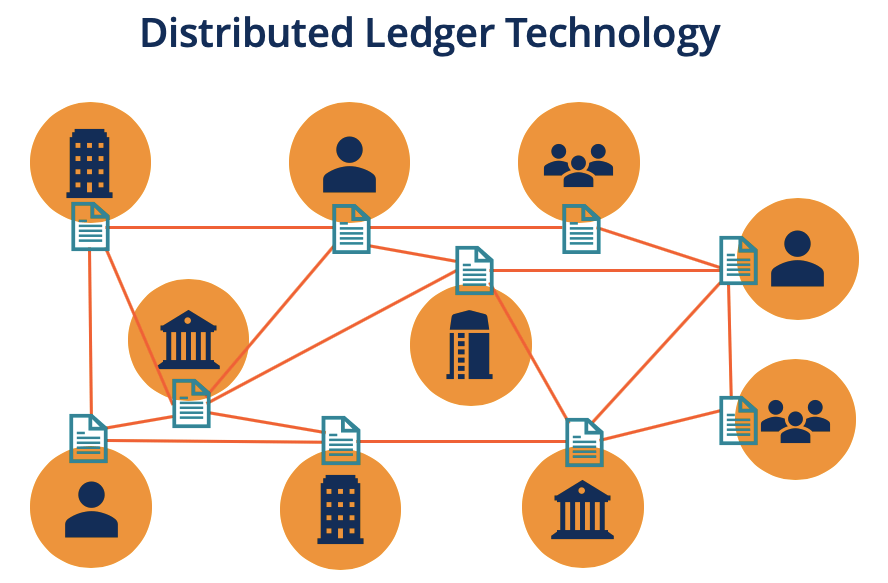
Distributed ledger technology versus centralized databases
DLT offers enhanced transparency and potential resilience through decentralization, yet it often faces challenges with transaction throughput compared to centralized databases. Centralized databases, like those used by the Bank of England's RTGS, provide high-speed processing and predictable latency. Most central banks currently favor centralized or permissioned DLT systems to maintain strict control over transaction finality.
Interoperability with existing payment rails
Integration with legacy infrastructure is a critical technical hurdle. A successful CBDC must communicate seamlessly with existing interbank settlement systems like SWIFT or local real-time gross settlement (RTGS) platforms. Failure to ensure this interoperability creates liquidity silos that hinder the adoption of the digital currency.
Case Study: The Bahamas Sand Dollar
The Sand Dollar, issued by the Central Bank of The Bahamas, serves as a practical example of a two-tier model. The central bank issues the currency, but authorized financial institutions (AFIs) manage the digital wallets and customer-facing services. This structure allows the central bank to maintain oversight while leveraging the existing reach and customer service infrastructure of local banks.
Risk management and compliance considerations
Regulatory impact varies significantly depending on the chosen model. The central bank must balance the need for anti-money laundering (AML) compliance with the public demand for financial privacy.
Data privacy and anonymity thresholds
Models that involve intermediaries often use tiered identity verification, where small transactions require less data collection than large ones. This approach allows for a degree of anonymity for low-value purchases while maintaining strict oversight for high-value transfers to prevent illicit activity. When considering the Top 10 digital identity verification companies for crypto in 2026, policymakers must ensure that these privacy thresholds align with broader societal expectations.
Cybersecurity resilience across issuance tiers
The distribution model defines the attack surface. A direct model centralizes risk, making the central bank a single point of failure. A two-tier model distributes risk across the banking sector, necessitating robust cybersecurity standards for all participating commercial banks to prevent systemic contagion.
Operational scalability and performance metrics
Scalability is the primary constraint for retail CBDCs. The system must support thousands of transactions per second (TPS) during peak periods, such as holidays or retail sales events.
Throughput and latency benchmarks
Performance expectations often mirror those of major credit card networks. While centralized databases currently handle higher TPS than most blockchain-based systems, ongoing developments in sharding and layer-two solutions are narrowing this gap. Institutions must benchmark their chosen model against current peak retail volume to ensure it can handle future demand without system degradation.
Hardware security modules and offline access
To ensure universal access, central banks are exploring hardware security modules (HSMs) integrated into mobile devices or smart cards. These allow for 'value-based' tokens that function similarly to physical cash, enabling offline transactions. This requires a secure enclave on the user's device to prevent double-spending without requiring a real-time connection to the central ledger.
Decision matrix for model selection
Selecting the appropriate model involves aligning institutional goals with technical capabilities. A step-by-step approach includes assessing the current banking sector's maturity, the necessity for offline transaction capabilities, and the desired level of central bank oversight. Institutions should prioritize models that allow for modular upgrades, ensuring the system remains relevant as payment technology evolves.
Frequently Asked Questions
Distinctions between CBDCs and cryptocurrencies
A CBDC is a centralized digital liability of a central bank, whereas cryptocurrencies are typically decentralized, private assets without government backing.
Legal tender status of CBDCs
Yes, CBDCs are designed to be digital versions of a nation's fiat currency and function as legal tender for all public and private debts.
Impact of CBDCs on commercial banking
CBDCs can compete with commercial bank deposits, potentially affecting bank liquidity and the traditional credit creation process.
Offline transaction capabilities for CBDCs
Some CBDC models are designed to support offline transactions using secure hardware, such as smart cards or mobile devices, to ensure accessibility.
Primary risks associated with CBDC implementation
Key risks include cybersecurity threats, potential for bank disintermediation, and challenges related to user privacy and data protection.
How are CBDCs implemented?
CBDCs are typically implemented through direct, indirect (two-tier), or hybrid models, depending on how much responsibility the central bank delegates to commercial intermediaries.

